24/7 emergency water damage. On site within 60 minutes.
24/7 emergency water damage. On site within 60 minutes.
Insurance
We work directly with your carrier: Xactimate estimates, daily drying logs and photos, and direct billing so you pay the deductible and nothing else on a covered loss. We cannot promise how a carrier rules. We can make sure the paperwork is not what holds you up. Call (910) 606-6161.
Watch: 33 seconds
Covered or not
The general rule on a homeowner policy: sudden and accidental is covered, slow and long-term is not. The details are in your policy, and we document the source so the claim is decided on facts.
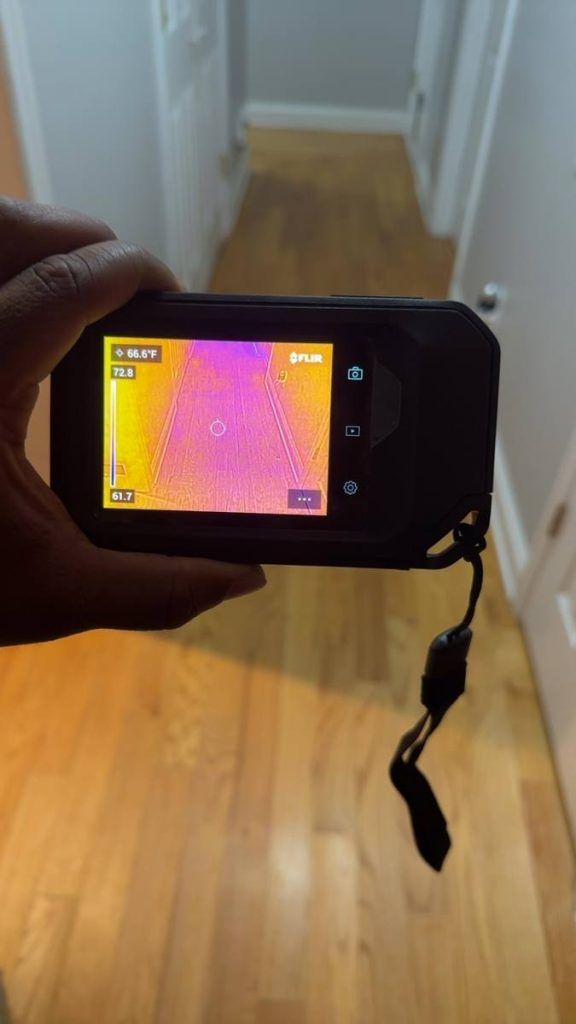
Usually covered when the failure was sudden.
A supply line that lets go, a PEX joint that fails or a pipe that freezes and splits is the kind of sudden loss a homeowner policy expects to pay for. The water damage is covered; the pipe repair itself often is not. A pinhole leak that ran for months is a different conversation, which is why we document how long materials have been wet.
Learn more →Usually covered when the failure was sudden.
Usually covered when the leak was sudden.
Usually covered.
Usually covered. Rising floodwater is not.
Only with a water backup endorsement.
Often capped, and only when a covered loss caused it.
Usually excluded.
Usually excluded. Documentation matters most here.
What we do on every claim
What we don't do: guarantee an outcome. The carrier decides coverage based on the policy and the cause. Our job is to make sure that decision is made on complete documentation.
On a covered loss we bill the carrier directly. You pay your deductible and nothing else unless the carrier denies part of the scope, and we tell you that before we do the work, not after.
If a claim is denied or you choose not to file, you get a written estimate before we start, and we tell you up front if a detailed written estimate carries a fee.
The inspection and moisture mapping are free either way.
How it works
Drying starts the same day. Waiting for an adjuster to visit before mitigation begins usually makes the loss bigger and the claim harder.
Photos and moisture readings of everything before it moves. This is the record the claim is built on.
You call your carrier and open the claim. Send us the claim number and the adjuster's name.
We write the Xactimate scope and send it with the drying logs and photos.
On site, walking the scope with the adjuster. Direct billing once the claim is approved.
You talk to the same person at every step. There is no claims department here, just the technician who did the work.
Call (910) 606-6161Insurance
Short answers to the questions we get on almost every claim.
Your policy pays for the damage, not the cause. On a burst pipe, the water damage is covered and the plumbing repair usually is not. Same with appliances and roofs.
Most carriers expect you to prevent further damage. That means calling for mitigation right away is not just allowed, it is usually required by the policy language. Photograph everything first, then call.
1. Call us so the drying starts.
2. Call your carrier and open a claim.
3. Send us the claim number and adjuster name.
We do the rest.
Paid once per claim, to us, on a covered loss. Not once per trade.
Some payments come in two parts: actual cash value first, the rest when work is complete. We keep the paperwork moving so the second check does too.
If part of the scope is denied, we tell you before doing that part and give you a written estimate for it.
Recent work
Real water and mold losses in the Triangle, documented and billed to the carrier.
Reviews
29 Google reviews from Raleigh-Durham homeowners, 5.0 average.
60 minutes
Emergency response
5.0 ★
29 Google reviews
IICRC
Water and mold certified
Insured
Liability coverage on file
Veteran-owned
Family and locally owned since 2025


FAQ
Should I call you or my insurance company first?
Call us first so the drying starts, then your carrier. Most policies require you to prevent further damage, and every hour materials stay wet adds to the loss.
Do you bill the insurance company directly?
Yes, on covered losses. You pay your deductible and nothing else unless the carrier denies part of the scope, and we tell you that before we do the work.
What is Xactimate?
The estimating software most carriers and adjusters use. Writing our scope in it means your adjuster is reading the same line items and pricing they work with every day, which cuts down the back and forth.
Will filing a claim raise my rates?
That is between you and your carrier, and it varies by company and claim history. We can tell you the size of the loss so you can decide whether to file.
What if my claim is denied?
You get a written estimate for the work and decide how to proceed. We do not start denied work without talking to you first.
Can you guarantee the claim gets paid?
No, and nobody honestly can. The carrier decides based on the policy and the cause. We make sure that decision is made on complete photos, readings and logs.
Call or text and the owner answers. If it is an emergency, say so and we roll.
Call (910) 606-6161